Mortgage Broker in Stafford Heights
fundfin. connects Stafford Heights residents with home loan solutions, investment loan options, and refinancing support across a wide panel of lenders.

Rated 5 from 82 Reviews
fundfin. connects Stafford Heights residents with home loan solutions, investment loan options, and refinancing support across a wide panel of lenders.
Rated 5 from 82 Reviews
Stafford Heights sits in Brisbane's inner-north, a suburb that has benefited from the same strong demand shaping the broader northern Brisbane corridor. With the median house price in neighbouring Stafford reaching $1,390,000 and vacancy rates in the area sitting at critically tight levels, the local property market is active and the decisions you make around your home loan or investment loan carry real weight. fundfin. is a Finance & Mortgage Broker serving clients in Stafford Heights, QLD and across Queensland, and our role is to help you cut through the complexity of mortgage comparison so you can make informed decisions with confidence.
Understanding the Stafford Heights Property Market
The northern Brisbane corridor, which includes Stafford Heights and its surrounding suburbs, has recorded some of the strongest house price growth in the Brisbane metropolitan area over the past 12 months. Suburbs like Kedron have seen house price growth of over 20%, while Stafford recorded nearly the same. This growth reflects genuine demand from both owner-occupiers and investors who recognise the value of proximity to the CBD combined with more accessible price points compared to inner-ring suburbs like Ashgrove, where the median house price sits above $1.9 million, or Wilston, where it exceeds $2 million. For buyers and investors considering Stafford Heights, understanding mortgage affordability in this context is essential, and that is where fundfin. adds real value.
As a Finance & Mortgage Broker near me for many Stafford Heights residents, fundfin. works with a broad panel of lenders to help you access competitive rates and loan features that suit your circumstances. Whether you are purchasing your first home, looking at buying an investment property, or considering refinancing a loan you already hold, the right structure matters as much as the interest rate itself.
Home Loans and Loan Structures That Fit Your Situation
One of the most important choices you will make when taking out a residential mortgage is the loan structure. A fixed interest rate loan gives you certainty over your repayments for a set period, which can be useful when budgeting in a rising rate environment. The RBA held the cash rate at 4.35% following its August 2026 meeting, and with several major banks forecasting at least one further increase before year end, understanding how your mortgage rates could move is a key part of planning. A variable interest rate loan, by contrast, moves with the market and typically comes with more flexibility, including features like an offset account and a redraw facility that can help you reduce the interest you pay over time.
For those who want elements of both, a split rate loan divides your borrowing between a fixed and variable portion, giving you a degree of certainty while retaining some flexibility. fundfin. can walk you through the differences and help you understand which structure aligns with your goals. We also help clients understand the comparison rate, which factors in fees alongside the headline interest rate, so you are comparing loans on a like-for-like basis rather than being drawn in by a low rate that carries hidden costs.
Investment Loans and Building a Property Portfolio
For investors, the Stafford Heights and broader northern Brisbane area presents a compelling case. Vacancy rates across suburbs like Stafford (0.54%), Kedron (0.82%), and Gordon Park (0.83%) are among the tightest in Brisbane, pointing to sustained rental demand. An investment property loan structured correctly can make a meaningful difference to your cash flow and long-term returns. fundfin. helps clients understand the difference between a principal and interest loan and an interest only loan, and how each affects your loan amount, your equity position, and your tax situation over time. Note that tax implications are a matter for your accountant, but fundfin. can help you understand how loan structure interacts with your investment strategy.
When assessing an investment loan, lenders will look closely at your loan to value ratio (LVR), which is the proportion of the property value you are borrowing. A lower LVR generally means access to more competitive rates and avoids the need for Lenders Mortgage Insurance (LMI), which is an additional cost that applies when you borrow above 80% of the property value. If you have built up home equity in an existing property, fundfin. can help you understand how that equity or cash deposit could be used to support a new purchase without triggering LMI.
Refinancing and the Home Loan Health Check
If you already hold a home loan, now is a worthwhile time to consider whether your current loan is still working for you. A home loan health check through fundfin. involves reviewing your current interest rate, loan features, and repayments against what is available in the market today. Many borrowers find they are paying more than necessary, particularly if their loan was established several years ago and they have not revisited it since. Refinancing a loan can potentially unlock interest rate discounts, access to an offset account, or the ability to make extra repayments without penalty.
fundfin. can also help clients understand rate lock options, which protect you against rate movements between loan application and settlement, and conditional approval processes that give you confidence to make an offer before your finance is fully formalised. Unconditional approval follows once all lender conditions are satisfied. Understanding stamp duty obligations is also part of the picture, and our stamp duty calculator can give you an early indication of what to budget for.
Whether you are searching for a Finance & Mortgage Broker near me in Stafford Heights or you are based elsewhere in Queensland, fundfin. offers a free service that can save time and help you access a broader range of lenders than approaching a single bank directly. Reach out to fundfin. today to discuss your home loan, investment loan, or refinancing needs.
Every home loan journey starts with a conversation. We take the time to understand your property goals, walk you through how the process works, and assess your current financial position. This gives you a clear foundation for identifying suitable loan options from banks and lenders across Australia.
A thorough review of your income, expenses, assets, liabilities, credit history, and available equity follows. This assessment determines your borrowing capacity and helps narrow down which loan products are most suitable for your circumstances. We also walk you through key concepts such as loan-to-value ratio (LVR), lenders mortgage insurance (LMI), and interest rate structures, so you understand exactly where you stand before moving forward.
With a clear picture of your finances, we compare loan products across multiple lenders, weighing up interest rates, fees, repayment terms, and features. We unpack the practical differences between fixed and variable rates and how each will affect your repayments, so you can choose a structure that aligns with your goals with confidence. Whether you are purchasing a home or exploring refinancing, we help you find a well-matched solution.
Securing pre-approval gives you a realistic budget and strengthens your position when making offers on properties. It signals to sellers that you are a committed buyer and gives you the confidence to move through the property market on your own terms.
Once you have selected your product, we take carriage of the formal application on your behalf. This includes managing the paperwork, coordinating supporting documents such as bank statements, and liaising directly with the lender, keeping you informed at every stage so there are no surprises.
Once your loan is approved, we guide you through reviewing the loan agreement, understanding all terms and conditions, and arranging any relevant insurance coverage. We also help you set up repayment options and map out strategies for managing your loan effectively over time.
At settlement, the lender formally advances the loan and ownership of the property transfers to you. We recommend engaging a solicitor or conveyancer to ensure this final step runs smoothly. From there, you will have online access to your loan and a clear plan in place to manage repayments with confidence.
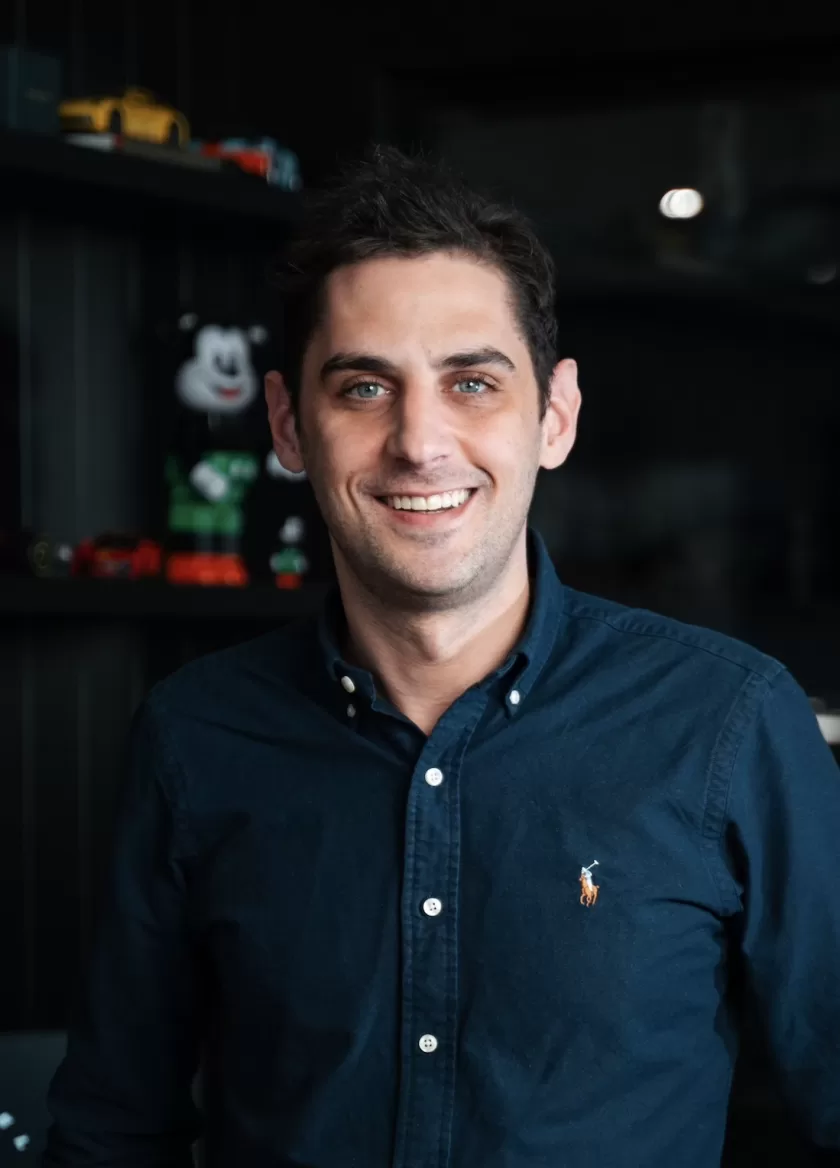
James Kristenson is a qualified Stafford Heights Mortgage Broker with over 12 years of experience across boutique finance firms and several major banks. During that time, he has helped a wide range of Queensland clients reach their property and finance goals through careful, tailored analysis of their individual circumstances.
Stafford Heights is an established suburb in Brisbane's northern suburbs, where family homes, proximity to Chermside and convenient access to the CBD appeal to both buyers and investors. James understands this local market and the lending considerations that shape outcomes for Stafford Heights buyers. His speciality lies in helping high-net-worth clients with residential, commercial and private banking solutions, working with individuals and business owners ranging from sole traders to corporate executives. He is known for finding solutions for clients that banks and other brokers place in the too-hard basket.
Whether you are pursuing a first home buyer strategy, structuring your investment lending, or seeking a refinance that genuinely improves your financial position, James brings the experience and local knowledge to help you move forward. Reach out to fundfin. today to get started.
Book AppointmentBC
Brad Cavanagh
James went to the nth degree to get my new loan and my refinances across the line. Can’t recommend highly enough. If you want no nonsense practice advice with strategic input from a bloke that gets it done. Trust me call James.
AR
Aaron Roberts
Honestly, James was fantastic. We used him as our mortgage broker up in the Grange/Windsor area and he made the whole process so much easier than we expected. He actually listened, explained everything properly without talking down to us, and found us a really good loan. Communication was always on point - never left us hanging or wondering what was happening. You can tell he knows the north Brisbane market well and just gets the job done without the drama. If you’re looking for a solid mortgage broker around Grange, Windsor or north Brisbane in general, give James a go. Would definitely use him again.
AS
Andrew Santoro
James recently assisted my partner and me with the purchase of our first home together. His professionalism, expertise, and guidance made the entire process seamless and stress-free. He was always approachable and willing to answer any questions we had along the way. We have no hesitation in recommending James to our friends and family and are grateful for the exceptional service he provided.
An offset account is a transactional account that sits against the loan. Any funds held in this account go to offsetting interest payable on the loan. For example, if your loan balance was $100,000 and you held $90,000 in your offset account, you would only be paying interest on $10,000. While the principal reduction repayments would remain the same, you would pay less interest over the life of the loan, thereby reducing the overall loan term saving you thousands or more! As with any everyday transactional account the funds are accessible at any time.
Generally if you are on a fixed rate loan you won't have access to an offset account however some lenders offer niche products that allow you to offset all or part of the fixed loan.
Redraw is where you make additional repayments above the minimum required as part of your loan contract. Some lenders allow you to draw on these additional repayments as required (sometimes for a fee) however this may impact on your loan balance and the interest payable.
Mortgage brokers operate independently of any financial institution. We're not locked into any relationships with specific lenders and want you to have the most competitive option based on your own unique set of circumstances. There is no 'one fit' solution for any client and we aren't limited to one lender's suite of products.
Best of all - there is no cost to you to use our service!
Yes you can. It comes down to the purpose and use of funds, as dictated by the appropriate lending guidelines.
For example, residential loan cannot be used for business purposes and vice-versa. We can assist in determining what loan is most suitable for your circumstances.
Not necessarily! Lenders Mortgage Insurance (LMI) is a premium charged by the lender's insurer for customers who need to borrow money above the maximum thresholds set by the insurer. Usually this is for loans above 80% loan to value ratio (LVR). However, some lenders offer LMI waivers for clients with certain professional qualifications up to 95% LVR, and other lenders may offer an alternate interest rate for customers with lower deposit without charging an LMI premium. There are also government backed first home buyer schemes which may allow for a deposit of 5%.
If you have any existing properties, you could also use the equity towards some or all of the deposit, including any associated costs such as stamp duty.
Some lenders also offer family pledge, or guarantor products where you can use the equity in a family member's home to borrow up to 100% of the purchase price plus costs.
Borrowing power is determinant on several factors. These can be a combination of, but are not limited to;
The lender
Your income (including rental income, pensions or super annuities, and government payments)
Your existing liabilities, such as credit cards, personal loans and HECS debts
Your monthly living expenses, fixed and discretionary
Lenders stress test the ability to afford loan repayments by running the loans against a floor rate, which is usually a couple of percentage points above the current market rate. This is to safeguard you in the event that if interest rates were to rise, you could still afford to make your repayments without experiencing significant hardship. Some lenders' floor rates are higher than others, meaning that you may be able to borrow more with Lender A than Lender B.
Existing debts, such as credit cards will also have an impact on how much you can borrow. While a $10,000 credit card might not seem like a lot in the scheme of things, it could be the difference of tens of thousands of additional borrowings on your home loan! This is where we can guide you to find the right options to suit your circumstances.
Absolutely - we can guide you through the entire process, from how much you can borrow, to first home buyers concession eligibility, putting you in touch with conveyancers and much, much more!
Absolutely, however it is important to note about what your goal actually is. For the sake of a few thousand dollars is it worth paying a few basis points more where any cash gain you have made will be eroded by the additional interest you're paying. If you have entered in to a longer loan contract, then you will likely end up paying more interest over the life of the loan, even if your initial rate is lower than what you were on.
Many lenders are offering rebates between $1000 and $4000 and some of these multiply per property refinance. We can discuss these options with you in your initial enquiry.


fundfin. ABN: 33 673 272 378, Fundfin Pty Ltd ABN: 33 673 272 378. Credit Representative #527192 is authorised under Australian Credit Licence #389328.
Disclaimer: This page provides general information only and has been prepared without taking into account your objectives, financial situation or needs. We recommend that you consider whether it is appropriate for your circumstances and your full financial situation will need to be reviewed prior to acceptance of any offer or product. It does not constitute legal, tax or financial advice and you should always seek professional advice in relation to your individual circumstances.
Site by Broker Studio