Mortgage Broker in Ashgrove QLD
Home loans, investment loans and refinancing solutions tailored to your goals in Ashgrove

Rated 5 from 81 Reviews
Home loans, investment loans and refinancing solutions tailored to your goals in Ashgrove
Rated 5 from 81 Reviews
Home loans, investment loans and refinancing for Ashgrove's established inner-north market. Book a free consultation.
5 stars from 81 reviews
Helping Ashgrove buyers and owners get the structure right
Ashgrove is one of those inner-north suburbs where the property has held its character while the market around it has kept moving. Leafy streets, good schools, and a short run into the city mean it stays in demand with owner-occupiers year after year. I'm James Kristenson, and I work with buyers, owners and investors across Ashgrove and the surrounding suburbs to get their finance structured properly, not just approved.
Working across a broad panel of banks and lenders means you're not limited to whatever one institution happens to offer. A fixed rate for certainty, a variable rate for flexibility, or a split of both, the right call depends on your situation, not a template.
First home buyers
Buying your first place in Ashgrove is a real financial commitment, and the groundwork matters. I'll walk you through your borrowing position, what grants and stamp duty concessions you're eligible for, and what loan-to-value ratio and LMI actually mean for your deposit, in plain terms. From there we look at lenders whose policies suit a first-time buyer's position and get you moving with a clear plan.
Home loans
Owner-occupiers in Ashgrove are competing for character homes that don't sit on the market long. I take the time to understand your income, your deposit or equity position, and what you're actually trying to achieve, then match that against lender policy, whether you're buying established or building. That groundwork is what lets you move quickly when the right property comes up.
Investment loans
Ashgrove continues to draw investors after long-term capital growth in a tightly held suburb. Interest-only or principal and interest, how you use equity, how your portfolio is structured, these decisions compound over time. I work across residential and commercial lending so your investment strategy is backed by a structure that actually supports it.
Refinancing
If you're already holding a loan against a property in Ashgrove, it's worth checking whether it's still working for you. I'll review your current loan against the market, including discharge fees and any break costs on a fixed rate, and give you a straight answer on whether refinancing makes sense for your position.
There's no cost to you for any of this. I also work with clients in Alderley, Newmarket, Wilston and Windsor, so if you're weighing up a move within the inner north, that's covered too.
How the process works
Initial consultation
— We talk through your goals, your financial position, and your timeline. This shapes everything that follows.
Financial assessment
— A full review of income, expenses, assets, liabilities, credit history and equity, so you know your borrowing capacity and where LVR, LMI and rate structures fit into your picture.
Comparing options
— I compare products across the lender panel on rate, fees, terms and features, and explain the practical trade-offs between fixed and variable.
Pre-approval
— Gives you a realistic budget and puts you in a stronger position with vendors.
Application
— I manage the paperwork, coordinate documents, and deal directly with the lender so you're not chasing anyone.
Approval
— We go through the loan agreement together, sort any insurance considerations, and set up a repayment approach that works for you.
Settlement and beyond
— Loan is advanced, ownership transfers, and I stay available as your situation changes.
About James
I've spent over 12 years across boutique finance firms and major banks throughout Queensland, and I specialise in high-net-worth clients across residential, commercial and private banking, from sole traders through to corporate executives. I've got a good handle on what makes Ashgrove and the inner-north corridor different from the rest of Brisbane's lending landscape, and I take on the situations other brokers and banks put in the too-hard basket.
Partnering with an Ashgrove Mortgage Broker means having a knowledgeable advocate in your corner from the first conversation through to settlement and beyond. Here is how fundfin. works with Ashgrove residents to make the lending process clear and purposeful.
Every home loan journey starts with a conversation. We take the time to understand your property goals, walk you through how the process works, and assess your current financial position. This gives you a clear foundation for identifying suitable loan options from banks and lenders across Australia.
A thorough review of your income, expenses, assets, liabilities, credit history, and available equity follows. This assessment determines your borrowing capacity and helps narrow down which loan products are most suited to your circumstances. We also walk you through key concepts such as loan-to-value ratio (LVR), lenders mortgage insurance (LMI), and interest rate structures, so you understand exactly where you stand before moving forward.
With a clear picture of your finances, we compare loan products across multiple lenders, weighing up interest rates, fees, repayment terms, and features. We unpack the practical differences between fixed and variable rates and how each will affect your repayments, so you can choose a structure that aligns with your goals. Whether you are purchasing a home in Ashgrove or exploring refinancing, we help you find a well-matched solution.
Securing pre-approval gives you a realistic budget and strengthens your position when making offers on properties. It signals to sellers that you are a committed buyer and gives you the confidence to move through the property market on your own terms.
Once you have selected your product, we manage the formal application on your behalf. This includes coordinating paperwork and supporting documents such as bank statements, and liaising directly with the lender, keeping you informed at every stage so there are no surprises.
Once your loan is approved, we guide you through reviewing the loan agreement, understanding all terms and conditions, and arranging any relevant insurance coverage. We also help you set up repayment options and map out strategies for managing your loan effectively over time.
At settlement, the lender formally advances the loan and ownership of the property transfers to you. We recommend engaging a solicitor or conveyancer to ensure this final step runs smoothly. From there, you will have online access to your loan and a clear plan in place to manage repayments with confidence. As your Mortgage Broker in Ashgrove QLD, fundfin. remains available after settlement to review your loan as your circumstances evolve.
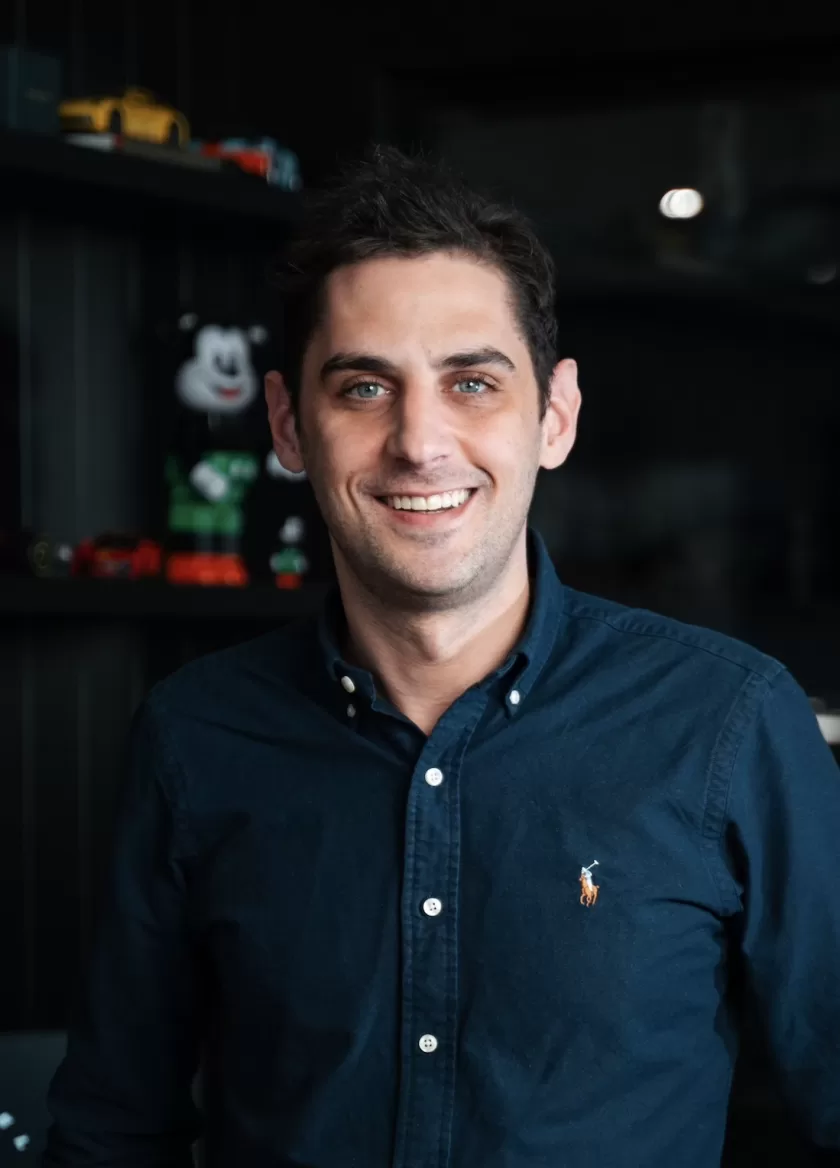
James Kristenson is a qualified Ashgrove Mortgage Broker with over 12 years of experience across boutique firms and several major banks. In that time, he has helped a wide range of clients across Queensland achieve their property and financial goals through diligent, tailored analysis of their individual circumstances.
Ashgrove's inner-north Brisbane location, strong school catchments, and consistent demand from families and professionals make it one of the more active lending markets in the region. James has a thorough understanding of this local property landscape and the broader corridor stretching toward Alderley and Newmarket, giving clients a genuine advantage when structuring loans in this area. Known for finding solutions that other lenders and brokers place in the too-hard basket, James specialises in working with high-net-worth clients on residential, commercial, and private banking solutions, from sole traders through to corporate executives. Learn more about the team at fundfin.
Book AppointmentAR
Aaron Roberts
Honestly, James was fantastic. We used him as our mortgage broker up in the Grange/Windsor area and he made the whole process so much easier than we expected. He actually listened, explained everything properly without talking down to us, and found us a really good loan. Communication was always on point - never left us hanging or wondering what was happening. You can tell he knows the north Brisbane market well and just gets the job done without the drama. If you’re looking for a solid mortgage broker around Grange, Windsor or north Brisbane in general, give James a go. Would definitely use him again.
AS
Andrew Santoro
James recently assisted my partner and me with the purchase of our first home together. His professionalism, expertise, and guidance made the entire process seamless and stress-free. He was always approachable and willing to answer any questions we had along the way. We have no hesitation in recommending James to our friends and family and are grateful for the exceptional service he provided.
VC
Vanessa Cuskelly
We had an outstanding experience with our mortgage broker from start to finish. James made what could have been a stressful process feel straightforward and manageable, always taking the time to explain our options and answer our questions clearly. His professionalism, knowledge, and attention to detail were exceptional, and he kept us informed every step of the way. We truly felt he had our best interests at heart and worked hard to secure the best outcome for us. We couldn't be happier with the service we received and would highly recommend James to anyone looking for a reliable, knowledgeable, and genuinely supportive mortgage broker. Thank you for making our home-buying journey such a positive experience!
An offset account is a transactional account that sits against the loan. Any funds held in this account go to offsetting interest payable on the loan. For example, if your loan balance was $100,000 and you held $90,000 in your offset account, you would only be paying interest on $10,000. While the principal reduction repayments would remain the same, you would pay less interest over the life of the loan, thereby reducing the overall loan term saving you thousands or more! As with any everyday transactional account the funds are accessible at any time.
Generally if you are on a fixed rate loan you won't have access to an offset account however some lenders offer niche products that allow you to offset all or part of the fixed loan.
Redraw is where you make additional repayments above the minimum required as part of your loan contract. Some lenders allow you to draw on these additional repayments as required (sometimes for a fee) however this may impact on your loan balance and the interest payable.
Mortgage brokers operate independently of any financial institution. We're not locked into any relationships with specific lenders and want you to have the most competitive option based on your own unique set of circumstances. There is no 'one fit' solution for any client and we aren't limited to one lender's suite of products.
Best of all - there is no cost to you to use our service!
Yes you can. It comes down to the purpose and use of funds, as dictated by the appropriate lending guidelines.
For example, residential loan cannot be used for business purposes and vice-versa. We can assist in determining what loan is most suitable for your circumstances.
Not necessarily! Lenders Mortgage Insurance (LMI) is a premium charged by the lender's insurer for customers who need to borrow money above the maximum thresholds set by the insurer. Usually this is for loans above 80% loan to value ratio (LVR). However, some lenders offer LMI waivers for clients with certain professional qualifications up to 95% LVR, and other lenders may offer an alternate interest rate for customers with lower deposit without charging an LMI premium. There are also government backed first home buyer schemes which may allow for a deposit of 5%.
If you have any existing properties, you could also use the equity towards some or all of the deposit, including any associated costs such as stamp duty.
Some lenders also offer family pledge, or guarantor products where you can use the equity in a family member's home to borrow up to 100% of the purchase price plus costs.
Borrowing power is determinant on several factors. These can be a combination of, but are not limited to;
The lender
Your income (including rental income, pensions or super annuities, and government payments)
Your existing liabilities, such as credit cards, personal loans and HECS debts
Your monthly living expenses, fixed and discretionary
Lenders stress test the ability to afford loan repayments by running the loans against a floor rate, which is usually a couple of percentage points above the current market rate. This is to safeguard you in the event that if interest rates were to rise, you could still afford to make your repayments without experiencing significant hardship. Some lenders' floor rates are higher than others, meaning that you may be able to borrow more with Lender A than Lender B.
Existing debts, such as credit cards will also have an impact on how much you can borrow. While a $10,000 credit card might not seem like a lot in the scheme of things, it could be the difference of tens of thousands of additional borrowings on your home loan! This is where we can guide you to find the right options to suit your circumstances.
Absolutely - we can guide you through the entire process, from how much you can borrow, to first home buyers concession eligibility, putting you in touch with conveyancers and much, much more!
Absolutely, however it is important to note about what your goal actually is. For the sake of a few thousand dollars is it worth paying a few basis points more where any cash gain you have made will be eroded by the additional interest you're paying. If you have entered in to a longer loan contract, then you will likely end up paying more interest over the life of the loan, even if your initial rate is lower than what you were on.
Many lenders are offering rebates between $1000 and $4000 and some of these multiply per property refinance. We can discuss these options with you in your initial enquiry.


fundfin. ABN: 33 673 272 378, Fundfin Pty Ltd ABN: 33 673 272 378. Credit Representative #527192 is authorised under Australian Credit Licence #389328.
Disclaimer: This page provides general information only and has been prepared without taking into account your objectives, financial situation or needs. We recommend that you consider whether it is appropriate for your circumstances and your full financial situation will need to be reviewed prior to acceptance of any offer or product. It does not constitute legal, tax or financial advice and you should always seek professional advice in relation to your individual circumstances.
Site by Broker Studio