Granny flat loans in Brisbane: how a second dwelling changes what you can borrow
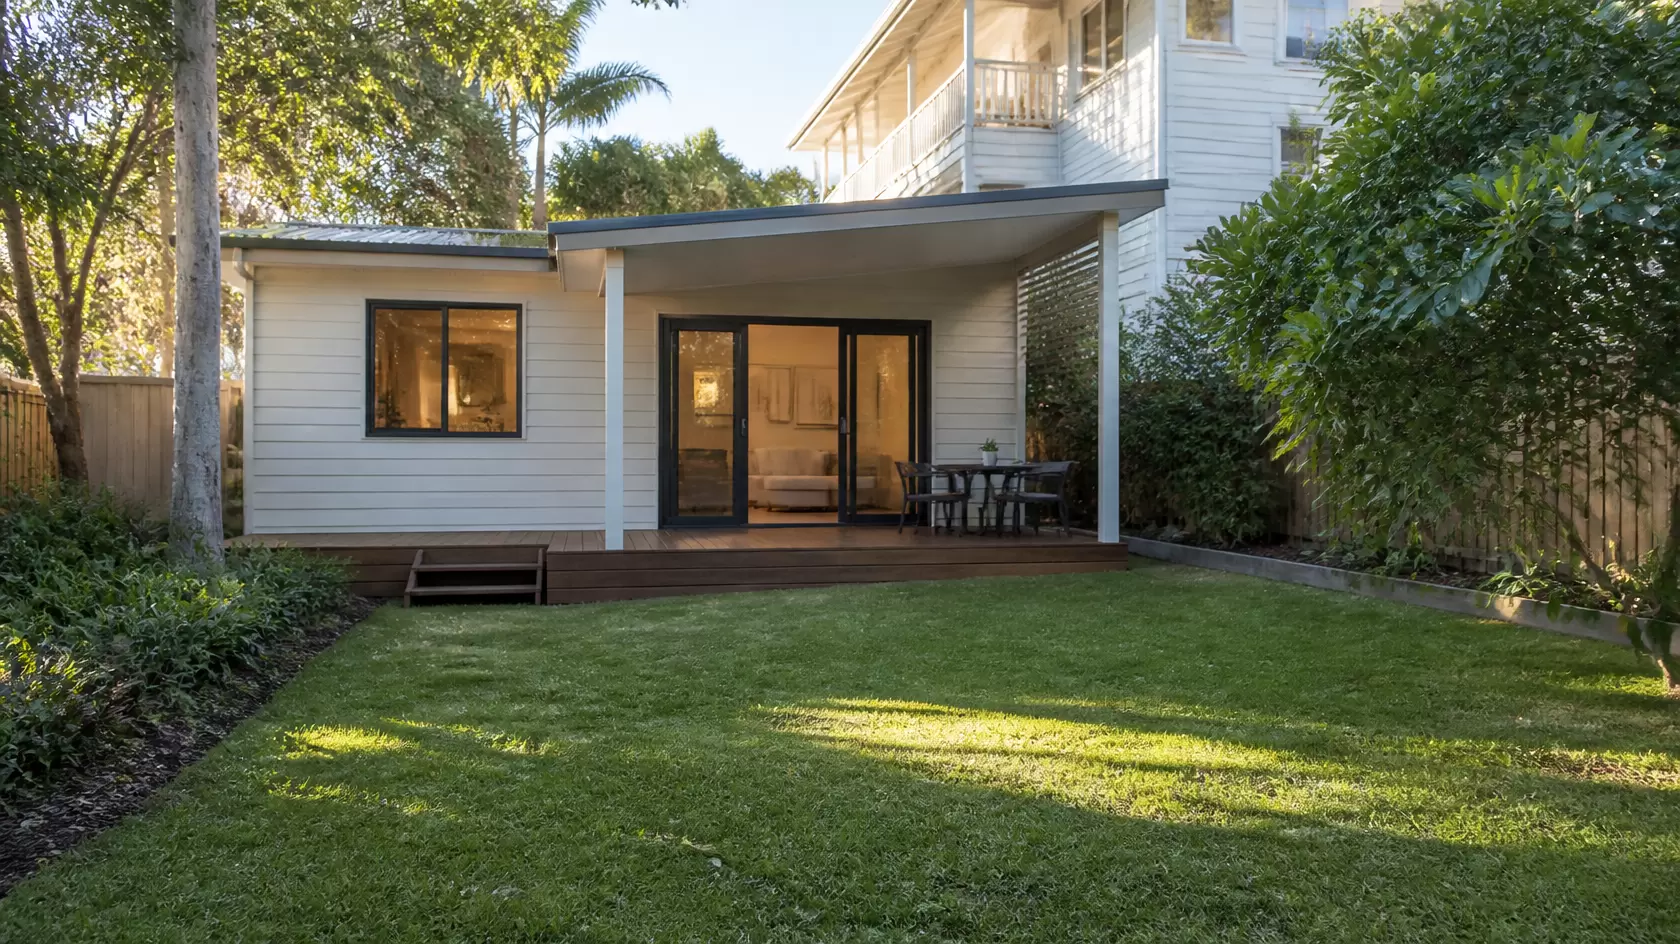
A granny flat used to be a family decision. In Queensland it is now a finance decision as well. Since the state changed its planning rules, a secondary dwelling can be rented to anyone, not just relatives. That has turned the backyard into one of the more practical ways to add income to a property you already own.
The finance side is less straightforward than most people expect. Lenders do not all treat granny flats the same way, and the difference can be tens of thousands of dollars in borrowing capacity.
A scenario from Alderley
A couple in Alderley had owned their home for around eight years. The block was larger than most in the street, with level access down the side and room at the back for a one-bedroom secondary dwelling. Their children were at school, their loan was well under 60% of the property's value, and they wanted the granny flat to cover part of the mortgage once it was built.
They had a builder's quote in the $180,000 to $230,000 range and had assumed their existing bank would simply increase the loan.
What made it harder than it looked
Two things got in the way.
First, their bank would lend the money but would not count any projected rent from the granny flat until it had been leased for a period. That left the couple borrowing the full build cost on their current income alone, which pushed serviceability closer to the limit than they were comfortable with.
Second, the bank wanted to release the funds as a lump sum top-up rather than a construction facility with progress payments. That meant paying interest on the whole amount from day one while the builder was still pouring the slab.
What we compared
We looked at how four lenders treat secondary dwellings, focusing on three questions:
- Will they count rental income from a granny flat at all, and at what percentage?
- Will they accept a rental appraisal before the dwelling is built, or only a lease after completion?
- Do they offer a proper construction loan for a secondary dwelling on an existing home, with progress draws?
The answers varied more than you would think. Some lenders shade granny flat rent more heavily than ordinary rent, or cap it. Others will use an on-completion valuation and a rental appraisal from a local agent, which is what made the difference here.
The outcome
The couple refinanced to a lender that would assess the projected rent from a written appraisal and fund the build through a construction facility. Interest was only charged on what had been drawn at each stage. The completed property was valued on an "as if complete" basis, which kept their LVR comfortable and avoided lenders mortgage insurance.
On their numbers, staying with the original bank and taking a lump sum would have cost several thousand dollars more in interest during the build alone, before counting the borrowing capacity they would have given up.
What to check before you start
- Approval comes first. In Brisbane a new secondary dwelling still needs building approval, and renting one out can trigger extra fire separation and sound requirements under the building code. Lenders will ask for approved plans.
- Get a rental appraisal early. A written appraisal from a local agent is often the document that decides how much a lender will count.
- Check the lender's policy, not just the rate. The cheapest rate is no help if the lender ignores the rent or will not fund progress payments.
- Think about how the loan is split. If the granny flat will be rented, keep its borrowing in a separate loan account. It makes the interest easier to track and may matter for tax. Talk to your accountant about the treatment.
- Valuation matters. An "as if complete" valuation can support a higher end value than the land and house alone.
Considering a granny flat?
If you have the space and want to know what you could borrow, our Borrowing Capacity calculator gives a starting point. For a proper look at which lenders will count the rent, book a time with us. We are on Days Road in Grange, a few minutes from Alderley.
Frequently Asked Questions
Can I rent out a granny flat in Brisbane?
Yes. Queensland's planning rules allow secondary dwellings to be rented to anyone, not just family members. A new granny flat still needs building approval, and renting it may require additional fire and sound work.
Will a lender count the rent from a granny flat?
Many will, but policies differ. Some need a signed lease, some accept a rental appraisal before construction, and some apply a lower percentage than they would to ordinary rent.
Can I use a construction loan to build a granny flat on my existing property?
Often, yes. Several lenders offer construction facilities for secondary dwellings with progress payments, so interest is only charged on the amounts drawn.